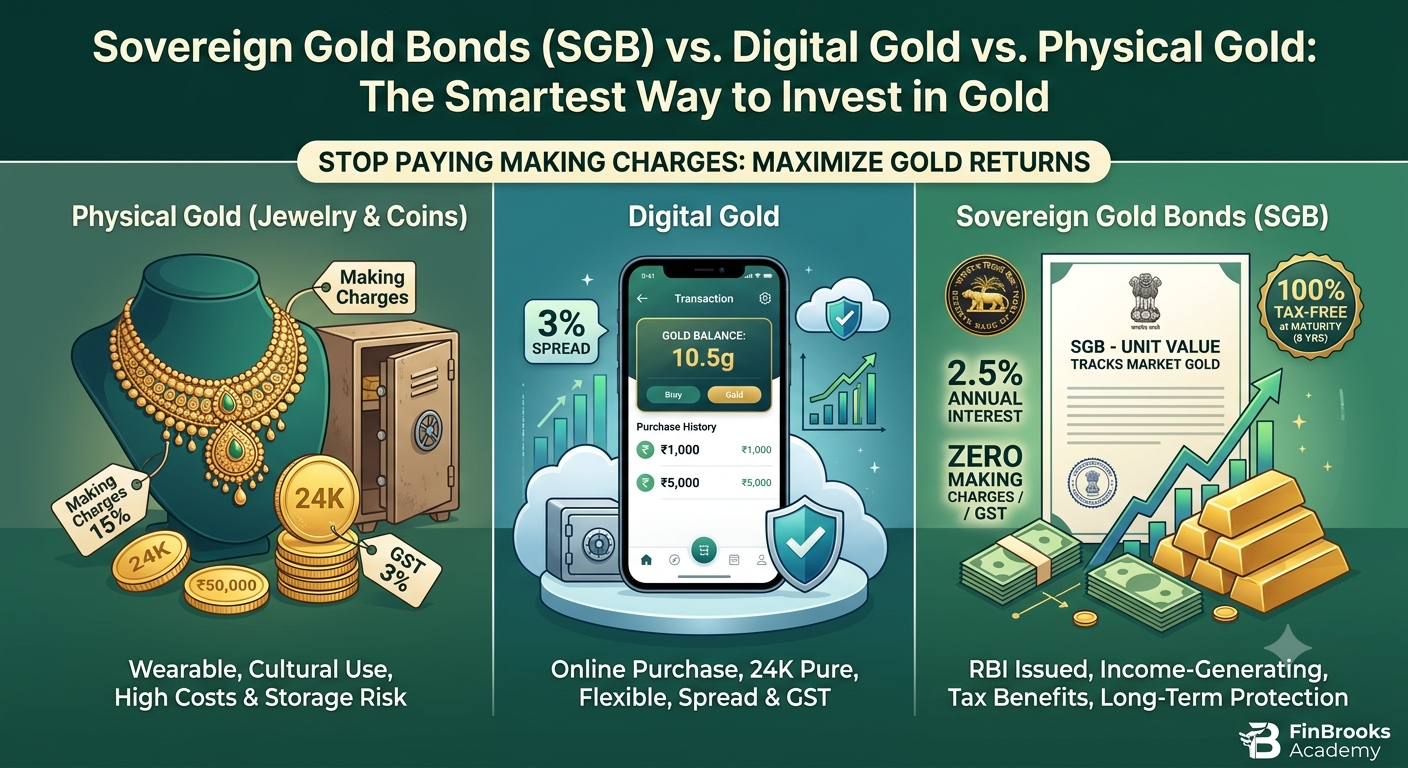
Stop Paying Making Charges: Why Digital & Sovereign Gold Beat Physical Jewelry Every Time
In India, gold is not just an asset class—it is deeply tied to culture, family security, and long-term savings. However, the traditional habit of buying physical gold in the form of jewelry, coins, or bars carries heavy hidden costs, including making charges (10%–25%), storage risks, purity concerns, and GST.
For modern wealth builders, holding gold digitally or through sovereign instruments yields far better net returns. Let us compare the three main ways to invest in gold and identify the absolute winner for your portfolio.
1. Physical Gold (Jewelry & Coins)
While physical gold provides tangible satisfaction, it is mathematically the worst way to invest money.
- Making Charges: You pay 8% to 25% extra as making charges, which cannot be recovered when selling.
- Taxes & Storage: Subject to 3% GST on purchase, ongoing locker charges, and constant theft risks.
2. Digital Gold
Digital Gold allows you to buy 24K pure gold online starting from as low as ₹10 (~$0.12) through fintech apps.
- Pros: Extremely liquid, highly flexible, and backed by physical gold stored in secure vaults.
- Cons: Incurs 3% GST on purchase and usually carries a 3% to 5% spread between buying and selling prices.
3. Sovereign Gold Bonds (SGBs)
Issued by the Reserve Bank of India (RBI) on behalf of the Government of India, SGBs represent paper/demat gold units that track the market price of 24K gold.
- 2.5% Annual Interest: Unlike physical or digital gold, SGBs pay a guaranteed 2.5% per annum interest on your initial investment amount, credited directly to your bank account every six months.
- Zero Tax on Maturity: If held for the full 8-year tenure, the entire capital gain is 100% tax-free.
- Zero Making Charges or GST: You pay zero GST and zero storage cost.
Gold Investment Comparison
| Feature | Physical Gold | Digital Gold | Sovereign Gold Bonds (SGB) |
| Making Charges / Fees | High (8% – 25%) | Spread (3% – 5%) | Zero |
| GST Applicable | 3% | 3% | Zero |
| Extra Income | None | None | 2.5% per year guaranteed |
| Tax on Capital Gains | Taxed as per holding period | Taxed as per holding period | 100% Tax-Free (at 8-year maturity) |
| Best Purpose | Wearable / Cultural use | Short-term emergency allocation | Long-term wealth protection & growth |
FinBrooks Reality Check
If you are buying gold for personal or cultural wear, physical jewelry is understandable. But if your goal is pure wealth preservation and growing capital, Sovereign Gold Bonds (SGBs) are the undisputed winner.
SGBs convert a non-yielding asset (gold) into an income-generating asset through the 2.5% annual payout while eliminating taxes, storage risks, and making charges completely.
Stay Ahead of the Market 📈
Subscribe to our weekly newsletter
Get your weekly market summary from FinBrooks Insights and smart financial lessons from FinBrooks Academy delivered straight to your inbox every weekend!